10 February 2026
Life Sciences Real Estate: Investor confidence is ‘quietly getting louder’

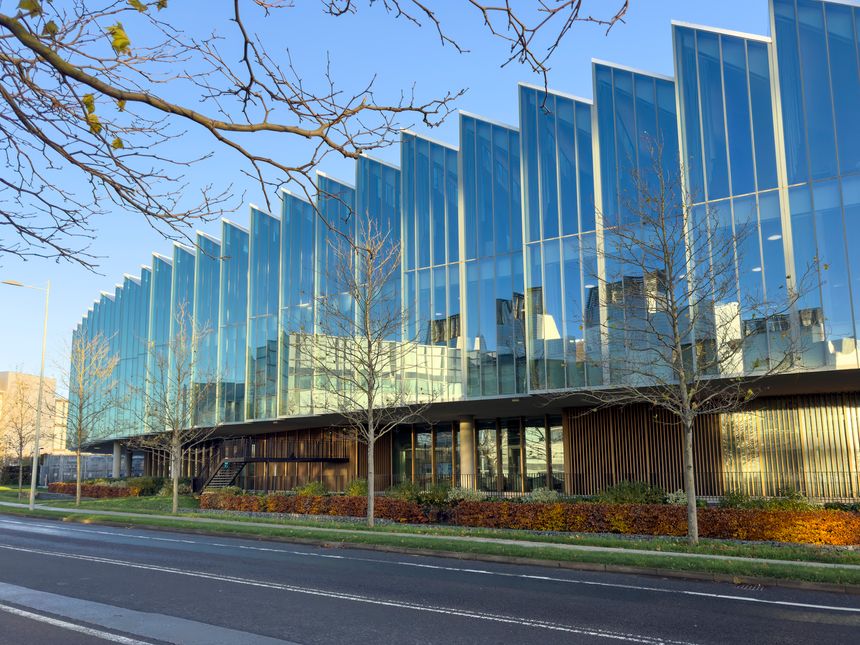
While the last 18 months have seen a period of adjustment, there are growing signs that UK life sciences real estate is settling into a more confident, investable phase. Certainly that is my reading of the recent Cushman & Wakefield ‘Marketbeat’ report for the Golden Triangle Life Sciences sector.
Market activity, during the second half of 2025 especially, suggests the sector is no longer being viewed purely as a defensive allocation. Instead, investors are beginning to differentiate — and that distinction is creating opportunity.
- Capital is still very much in the market
Investment interest across the Golden Triangle remains robust, with £985m invested across three transactions. While pricing discipline has increased, life sciences assets continue to attract capital, particularly where location, quality and long-term income prospects align.
This reflects a broader shift: investors are not stepping back from the sector, but leaning into assets they understand well and can underwrite with confidence.
- A more balanced development pipeline
Although there is still a significant amount of lab space under construction (3.6m sq ft), the pace of new schemes entering the pipeline is slowing. That moderation is healthy.
For investors, a more controlled supply outlook supports rental stability – with quoting rents in Q4 2025 holding steady at £70psf in Oxford, £77psf in Cambridge and £140psf in London. This also improves the prospects for well-designed schemes reaching the market over the next few years.
- Strong foundations on the occupier side
Life sciences occupiers continue to prioritise high-quality, well-located space. Demand is particularly strong for buildings that are ready to use, flexible, and embedded within established innovation clusters. Take up across the Golden Triangle reached 556,700 sq ft in Q4 2025 – the highest quarterly total in over a decade.
While funding conditions remain selective (£524.5m raised in venture capital only, over 30% below the 5-year average), the underlying strength of the UK’s research base continues to support occupier demand — and, in turn, investor confidence.
What this means for investors in 2026
The current environment favours:
- assets with clear income potential or short paths to letting,
- schemes aligned to broader innovation ecosystems rather than single-use campuses, and
- long-term strategies that focus on quality and resilience rather than rapid turnover.
Life sciences real estate is moving beyond the volatility of recent years. For investors willing to be selective, the outlook is increasingly positive — with opportunities emerging in assets that combine strong fundamentals with long-term relevance.
KEY TAKEAWAYS FOR Q4 2025 - Take-up across the Golden Triangle reached 556,700 sq ft in Q4 2025, marking the highest quarterly total in over a decade. Prime quoting rents across the Golden Triangle held steady in Q4 2025, with Oxford at £70.00 psf, London at £140.00 psf, and Cambridge unchanged at £77.00 psf. - Two schemes totalling 176,600 sq ft reached completion across the Golden Triangle during Q4. A further 3.6 million sq ft of lab space remains under construction. - UK life sciences companies raised £524.5 million in venture capital, remaining 33.5% below the five-year quarterly average. - Investment volumes in the Golden Triangle life sciences real estate market reached £985 million across three transactions.
Subscribe to our latest insights by topic here.
 Chris Xitsas
Partner, Commercial real estate