28 September 2026
PBSA: is scale still the answer?
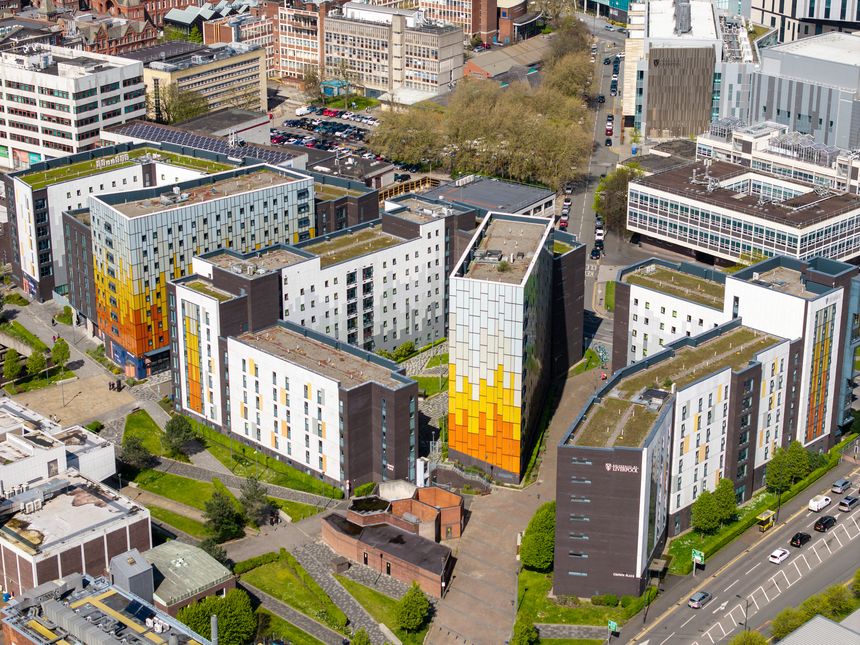
I attended Bisnow’s Student Accommodation Summit last week, where the first panel focused on “capital, consolidation and the cost of doing business” in UK PBSA.
The discussion left me with one particularly interesting thought: scale may still matter, but scale for its own sake is not necessarily the answer.
The market is clearly more challenging than it was during the period of cheap capital and strong rental growth of the mid-late 2010s. Investors now have to be more selective, financing is more costly and complex/structured, and underwriting must be more focused on the quality and durability of income rather than simply headline rental growth.
One observation from the panel particularly struck me: “scale isn't necessarily better – scale is about discipline and efficiency.” That feels increasingly relevant to PBSA, where the operator platform is becoming critical. Income is made – or lost – on operational execution. Scale can create efficiencies, but only if those efficiencies translate into better operational performance, higher occupancy levels and ultimately more resilient income.
The panel also highlighted how much more granular the investment analysis has become. The specific higher-education establishment, micro-location, asset quality, student demographics and the ability to manage the operational cost base are all increasingly important. PBSA is no longer simply a single investment proposition.
Liquidity is returning – but perhaps not quite as quickly or as broadly as the headline numbers suggest. Knight Frank reported £2.1bn of UK PBSA investment in Q1 2026, the strongest first quarter for more than a decade. But the detail is revealing, as CBRE's mid-year review observes also: only 20 transactions completed, broadly in line with long-term norms, with five deals exceeding £150m. The £720m acquisition of Empiric by Unite was a particularly significant contributor. In other words, the market was “capital heavy, but not deal heavy” and that distinction feels important. There is clearly capital available for the right opportunities, but this is not yet a broad-based reopening of the market.
At the same time, the panel was keen to stress, there is a feeling that valuations may still have some catching up to do, particularly where historic underwriting has relied heavily on continued rental growth.
Perhaps the most encouraging takeaway was that, despite the noise, the fundamentals of UK PBSA remain compelling. Occupancy is stabilising around the mid-90%, supply remains constrained in many markets (due to viability issues) and there is still significant institutional appetite.
The market may therefore be moving into a different phase: less about chasing growth at scale and more about demonstrating genuine operational discipline, resilient income and asset-level quality.
For PBSA investors and operators, that may ultimately prove to be a healthier test of the market.
CAPITAL, CONSOLIDATION & THE COST OF DOING BUSINESS: MERGERS, MARGINS & THE MARKET REALITIES RESHAPING UK PBSA
Subscribe to our latest insights by topic here.
 Chris Xitsas
Partner, Commercial real estate